Archive for the ‘Opinion’ Category

Analysis: Antioch’s General Fund continues to subsidize water park, golf course at almost $2 million per year

Thursday, August 27th, 2026
More than enough for both the Homekey+ program and Rivertown Square project

“We need to be fiscally prudent by closely monitoring expenses…and minimize General Fund subsidies to high-cost operations, such as the golf course and water park.” – then-City Manager Ron Bernal in 2017-19 Budget message

By Allen D. Payton

In spite of the Antioch City Council’s reasons for voting against pursuing a state grant for the Homekey+ program for veterans and the homeless at the Antioch Inn & Suites and paying for maintenance for a new Rivertown Square park in downtown, the City’s General Fund continues to subsidize recreation at both the Antioch Water Park and Lone Tree Golf & Event Center at a cost of almost $2 million per year.

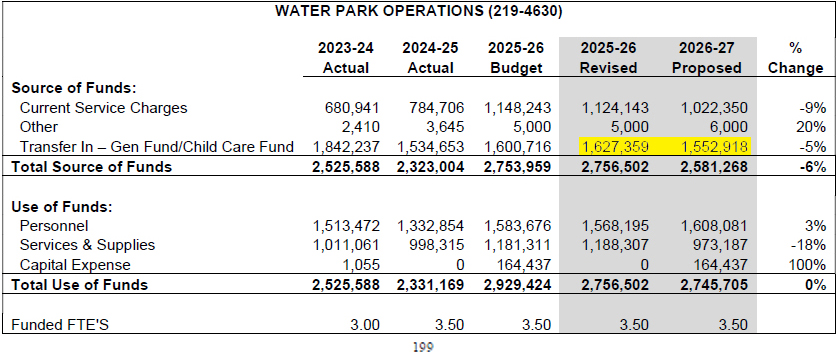
This past fiscal year, the water park received over $1.6 million to subsidize its operations, and the budget allows for $1.55 million in this fiscal year. In addition, the golf course receives almost $500,000 in debt service and water costs.
According to the City’s Adopted Fiscal Year 2026-27 Budget, “Parks and Recreation provides the City’s residents recreational, preschool, social and meeting space within the community. Recreation Programs are accounted for in the Recreation Special Revenue Fund. The Recreation Support division within the General Fund provides a subsidy to this fund to support operations.”

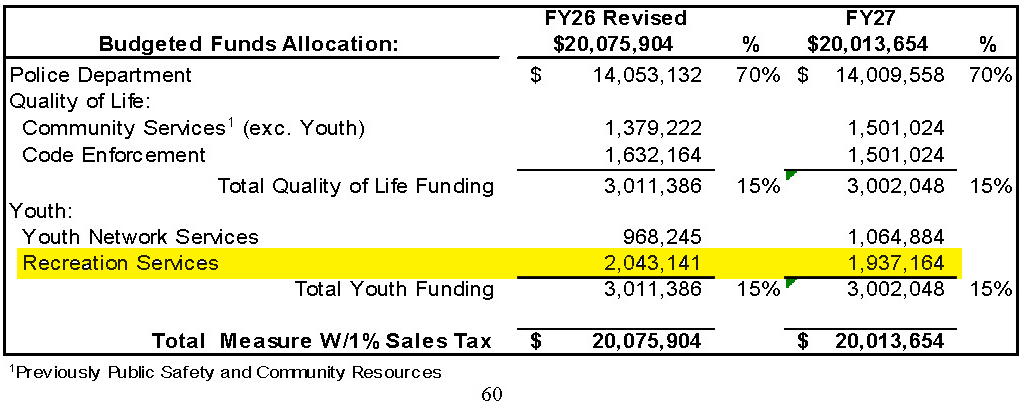
The General Fund budget shows Recreation Services Support (Recreation Department) receiving $4,812,031, a 12% decrease from the $5,479,935 in the Revised 2025-26 Budget. Of that amount, Recreation Services was approved to receive $1,937,164 from the City’s Measure W one-cent sales tax or 9.7% of the total revenue of over $20 million from that source. The amount makes up 40% of the total budget for the Recreation Department.
Antioch Water Park Subsidy

According to the Fiscal Year 2026-27 City Budget, the Antioch Water Park will receive $1,552,918 from the General Fund and Child Care Fund, of which $87,500 is from the latter, a 5% reduction from the subsidy of $1,627,359 in the Revised 2025-26 Fiscal Year Budget. That totals 60 percent of the water park’s revenue with the difference generated by Current Service Charges, which includes gate fees to enter the park and $111,000 in concession sales from Gator Grill and Allie’s Oasis.

According to Parks & Recreation Director Shahad Wright, “From the last supervisor report, we had over 30,000 guests but there is no breakdown for kids or adult that I can currently pull.”
Lone Tree Golf & Event Center Subsidy

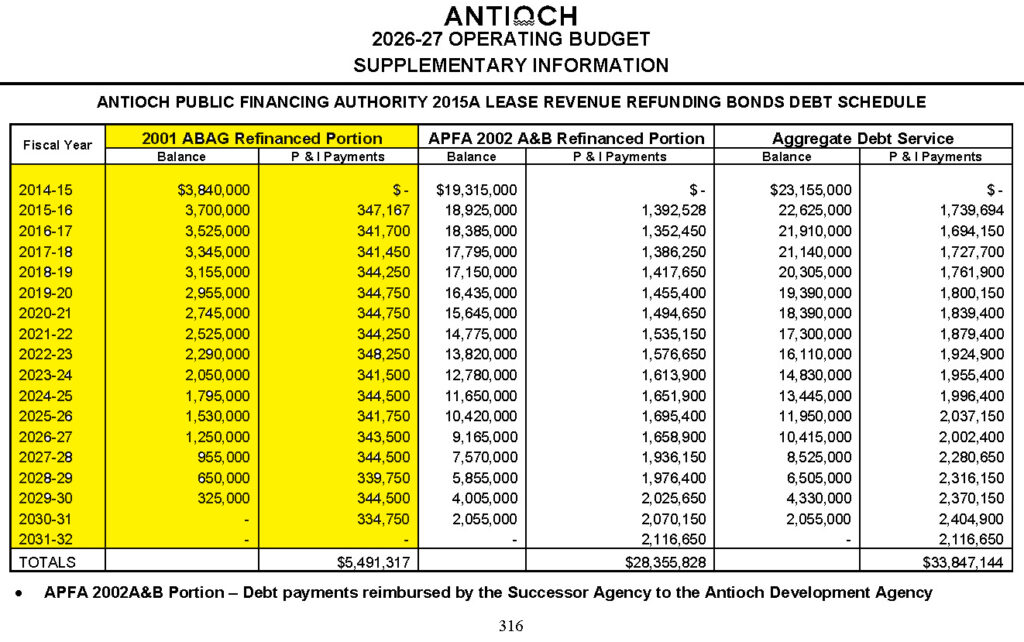
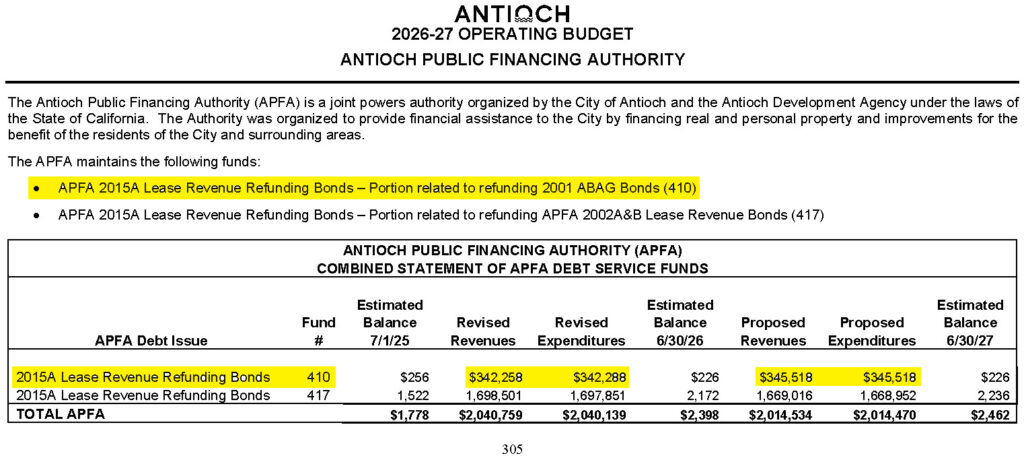
Although this and last year’s City Budgets do not mention the Lone Tree Golf & Event Center (LTGEC), City Finance Director Dawn Merchant shared, “One of the transfers out to the 2015A debt service fund ($345,518 in FY26/27) is for that debt.  The General Fund also pays for water at the golf course when they utilize City water (the Golf Course pays Delta Diablo directly for any irrigation water through them).  We budget $150K per year, but the amount really fluctuates.”

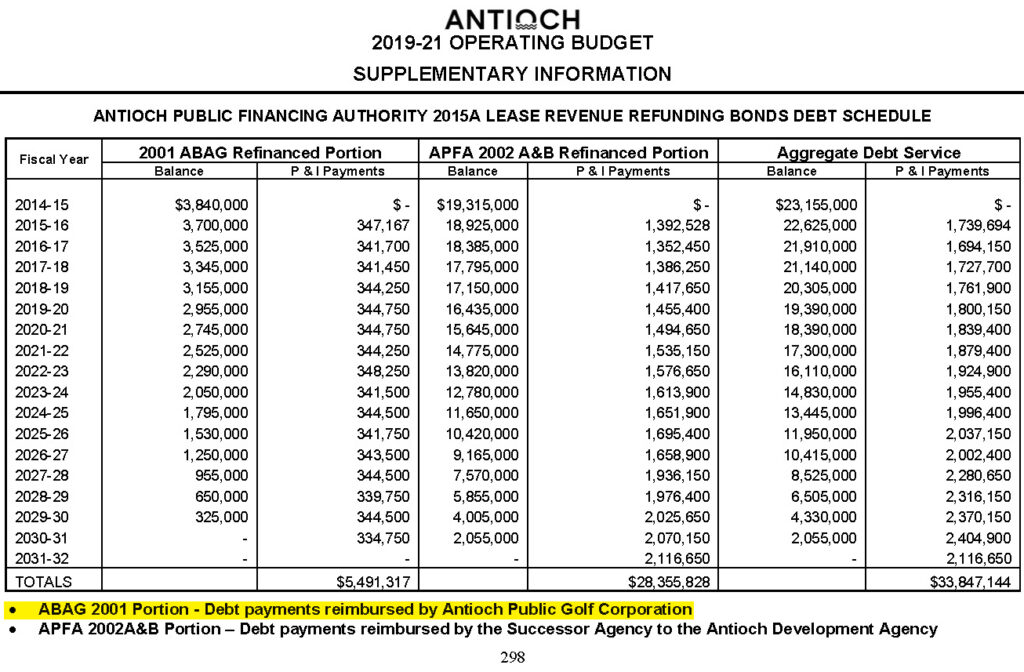
Of the $345,518 amount, $343,500 will be used this year to pay the debt for improvements to the golf course and expansion of the event center in 2002. It’s shown in the budget as Antioch Public Financing Authority Debt Service Fund 410 (see page 45) and after this fiscal year’s payment, “the ABAG (Association of Bay Area Governments) portion of the debt will be $1,250,000 at 6/30/27 principal and $343,500 interest outstanding. The debt schedule is on page 316 of the budget,” she added.
Over 53,000 Rounds of Golf in FY25-26

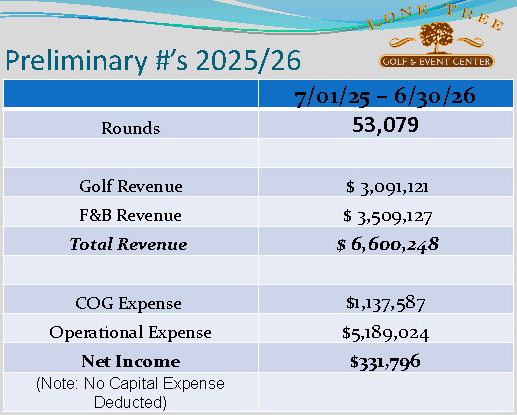
According to Wright’s Lone Tree Golf Course Annual Operations Update for Fiscal Year 2025-26 to the Antioch City Council’s Committee for the Lone Tree Golf Course consisting of Mayor Ron Bernal and District 4 Councilwoman Monica Wilson, there were 53,079 rounds of golf played between July 1, 2025, and June 30, 2026. (COG means Cost of Goods)

The report also shows total revenue for the year of $6,600,248 with $3,091,121 from golf, of which $570,678 was generated by the driving range, and $3,509,127 from food and beverages at the Event Center, which includes Champions Bar & Grill and the banquet facility.

Expenses include Cost of Golf at $1,137,587 and Operational at $5,189,024 for Net Income of $331,796. However, as the report points out there is, “No Capital Expense Deducted” from the total included. That would be the $345,518 for debt service mentioned above. So, the LTG&EC actually experienced a net loss of $13,722. But the $331,796 remains within the facility’s budget and is not used to reimburse the City’s General Fund.

Basically, the General Fund is providing a subsidy of over $9.00 per round of golf to those who enjoy playing the sport in Antioch.
Golf & Event Center Previously Mentioned in City Budgets

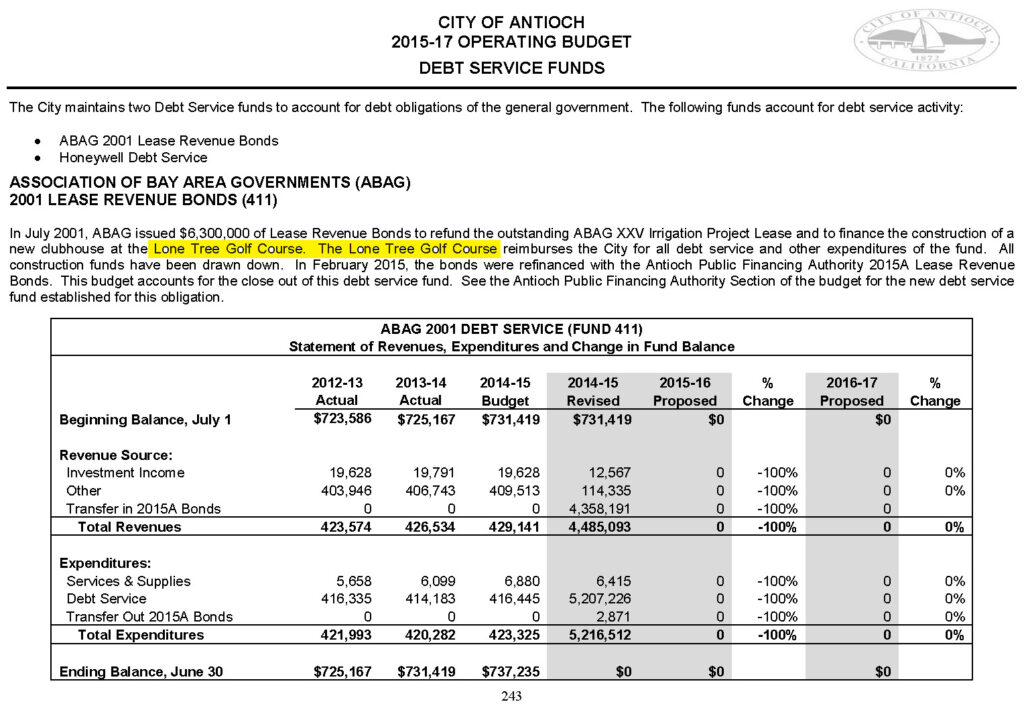
The LTG&EC was mentioned in the 2014-15 and 2015-17 Budgets, twice on page 243. That reads:

“ASSOCIATION OF BAY AREA GOVERNMENTS (ABAG) 2001 LEASE REVENUE BONDS (411)

“In July 2001, ABAG issued $6,300,000 of Lease Revenue Bonds to refund the outstanding ABAG XXV Irrigation Project Lease and to finance the construction of a new clubhouse at the Lone Tree Golf Course. The Lone Tree Golf Course reimburses the City for all debt service and other expenditures of the fund. All construction funds have been drawn down, and the final debt service payment will be made in July 2031.”

The same message on that same page was included in the FY2015-17 Budget.
Golf Course & Event Center No Longer Reimburses General Fund, Debt No Longer Mentioned in Budgets

But the debt for the LTGC/LTG&EC was no longer mentioned and the golf course only referred to twice in the FY2017-19 Adopted Budget. On Page iii of then-City Manager Ron Bernal’s budget message it reads, “We need to be fiscally prudent by closely monitoring expenses…and minimize General Fund subsidies to high-cost operations, such as the golf course and water park.”

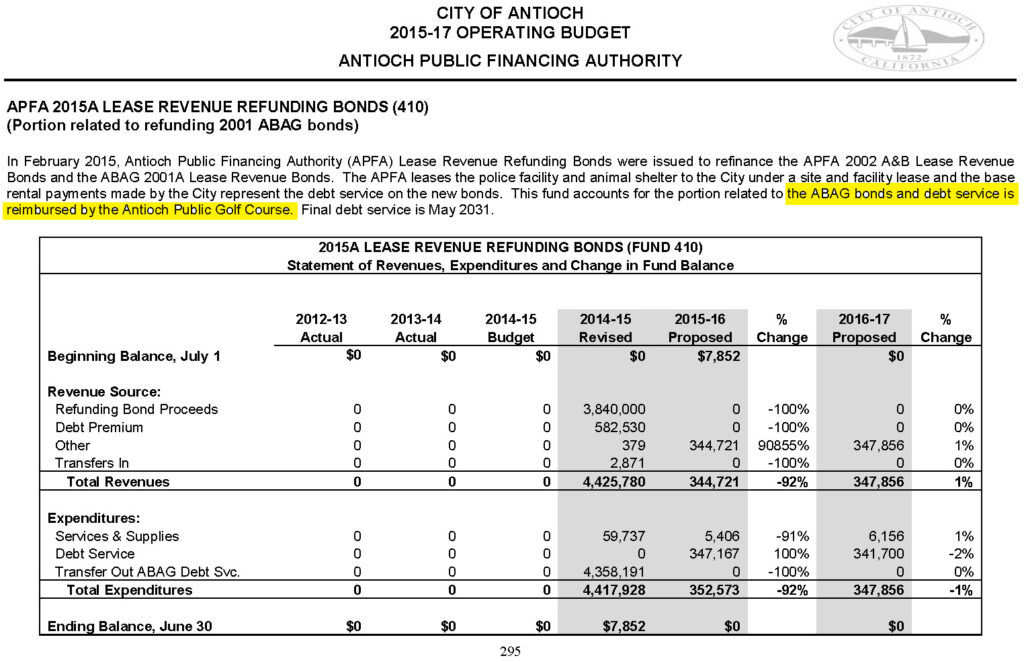
Then on the Supplemental Information page 295 a note at the bottom reads, “ABAG 2001 Portion – Debt payments reimbursed by Antioch Public Golf Corporation.” The same note was provided on the same page of the FY2019-21 Budget. But it was no longer included as of the FY2021-23 Budget.

Merchant was asked if that is because the debt payments have no longer been reimbursed by the Golf Corporation as of FY2022.

She responded, “You are correct that the reference was removed once the Golf Course stopped reimbursing the City. The debt service payments show in the 2015A Lease Revenue Refunding bonds debt service fund.  The transfer out in the General Fund is to move money to that debt service fund for payment of the debt service.”

“As you can see from the report Shahad prepared that you provided, the City’s agreement with the Golf Course only requires that they pay us a small annual fee that is escalated by CPI,” she continued. “Many years ago, due to financial stress at the Golf Course, City council agreed to take on the burden of the debt service within the General Fund and not seek reimbursement from the Golf Course for debt service, and thus the current agreement in place.”

Merchant also shared, “The expenses related to the Golf Course were discussed at the (Council’s) budget meetings held on April 21st and May 5th.”
More Questions for Merchant

Merchant was also asked since there are expenses for the Golf & Event Center from the General Fund, why isn’t it mentioned anywhere in the budget? Shouldn’t it be for full transparency to the public?

What I see is on page 306 of the Adopted Budget, entitled, “APFA 2015A LEASE REVENUE REFUNDING BONDS (410) (Portion related to refunding 2001 ABAG bonds)” it reads, “In February 2015, Antioch Public Financing Authority (APFA) Lease Revenue Refunding Bonds were issued to refinance the APFA 2002 A&B Lease Revenue Bonds and the ABAG 2001A Lease Revenue Bonds. The APFA leases the police facility and animal shelter to the City under a site and facility lease and the base rental payments made by the City represent the debt service on the new bonds. This fund accounts for the portion related to the ABAG bonds and debt service is paid by the General Fund. Final debt service is May 2031.”

Then on page 307, entitled, “APFA 2015A LEASE REVENUE REFUNDING BONDS (417) (Portion related to refunding APFA 2002 A&B Lease Revenue Bonds)” it reads something very similar: “In February 2015, Antioch Public Financing Authority (APFA) Lease Revenue Refunding Bonds were issued to refinance the APFA 2002 A&B Lease Revenue Bonds and the ABAG 2001A Lease Revenue Bonds. The APFA leases the police facility and animal shelter to the City under a site and facility lease and the base rental payments made by the City represent the debt service on the new bonds. This fund accounts for the portion related to the 2002 A&B bonds and debt service is reimbursed by Successor Agency to the Antioch Development Agency. Final debt service is May 2032.”

So, if all the money shown on page 306, $345,518, is spent for the Golf & Event Center debt, shouldn’t the information in the chart on that page be about the Golf & Event Center not about the police facility and animal shelter?

Also, on page 45, entitled, “Transfers By Fund”, I think it would be best that under Antioch Public Financing Authority Debt Service Fund 417 it shows “Police Facility and Animal Shelter” and under Fund 410 it shows, “Lone Tree Golf & Event Center” for full transparency to the public (and media).
Merchant Explains Debt for Golf Course, Police Facility & Animal Shelter Combined When Refinanced

In response, Merchant wrote, “The reason on page 306 (and 307) it references the police and animal shelter is because when the ABAG bonds were refinanced with the 2015A lease revenue bonds, to secure the bonds, the Antioch Public Finance Authority entered into a lease agreement with the City for the Police and Animal Shelter essentially being the security for the bonds thus providing a ‘lease payment’ as debt service for the bonds.  The Golf Course provides no security for payment of the bonds.”

“I note your comment about the transfers schedule,” she added. “The titles on page 45 represent the actual fund names in the City’s general ledger accounting system, as do all the transfers listed on the schedule.”

Conclusion – It All Comes Down to Priorities

During a recent council meeting on the Homekey+ program, a resident suggested the Golf Course should raise rounds by just $5.00. If they did, that would generate another $265,000 per year, which, along with the current net revenue, would be enough to cover the costs of water and the debt payment.

In addition, while I was a council member when the water park first opened, I suggested contracting out the operations to a private company. I called one in Sacramento. They said they were interested but were in the process of opening Water World (now Six Flags Hurricane Harbor) in Concord at the time. Perhaps, another private company might be interested, now. All it takes is a phone call to start the process. If it were contracted out, that would eliminate the $1.5 million annual General Fund subsidy.

Combine that amount with requiring the Golf Course Board to reimburse the City for the cost of both the water and bond debt payment for a total of almost $500,000, and Antioch’s General Fund would enjoy almost an extra $2 million per year. That’s more than enough to cover the $1.2 million annually for the Homekey+ program and to cover the estimated $250,000 annual maintenance costs of the Rivertown Square project on the former Beede Lumber Company lot in downtown.

It all comes down to priorities. The Council can continue to subsidize the recreation of some – who don’t all live, here which was an argument about not funding the Homekey+ program – or house some of our homeless residents, reducing their impact on our businesses, police department, Code Enforcement and City budget, and add a new, long-planned park and event center in the City’s historic downtown.

I believe it’s time Mayor Bernal and the rest of the council members heed his message from when he was city manager and, of less importance, ensure the debt for the golf and event center be clearly listed in each year’s budgets for full transparency to the public.
CA’s mixed-sex bathroom law kicks in just before school starts

Thursday, July 23rd, 2026
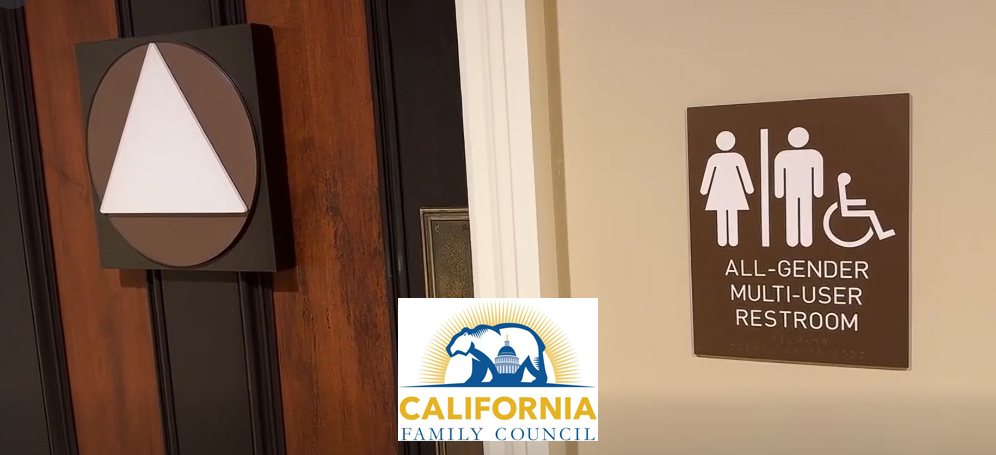
All-gender restroom in California’s State Capitol building. Video screenshot source: CA Family Council

“The law requires that every school campus have at least one all-gender restroom option available to students.”

By Greg Burt, Vice President, California Family Council

SACRAMENTO, CA — California is quietly moving toward mixed-sex bathrooms in K-12 public schools, and the state’s own Department of Education is leading the way.

A new law California Family Council opposed, SB 760, now requires schools to provide at least one “all-gender” restroom option on campus.

Passed in September 2023, the bill was cosponsored by then-State Senator Steve Glazer (D-Orinda). He, then-State Senator Nancy Skinner, now-State Sen. Tim Grayson and Assemblymembers Rebecca Bauer-Kahan, Buffy Wicks, and Lori Wilson who represent Contra Costa County, voted for the bill.

The stated goal was to make transgender-identified students feel safer from bullying. But in the rush to accommodate those students’ feelings, lawmakers apparently gave little thought to a different safety question: what happens when boys are given access to girls’ bathrooms and locker rooms?

The State Is Already Building the Roadmap

The California Department of Education has an entire webpage dedicated to “All Access Restrooms,” describing it as a resource offering background information, planning and design resources, laws and regulations, and references for implementing “gender-inclusive” restrooms in K-12 schools.

The background information on that page acknowledges that “the designs of all-access restrooms have been trending in schools throughout the state, the country, and the world,” while noting there are currently no California design standards for these facilities. In other words, the trend is already underway, and the standards are still catching up.

The planning section of the CDE page is even more candid about the scope of what is being proposed. It describes “shifting from multi-user gendered restrooms and single-user all-gender restrooms to offering blocks of restroom facilities for all students;” meaning the goal is not just a single converted nurse’s bathroom tucked in a hallway. The ambition is to redesign entire blocks of school restroom facilities so that boys and girls share the same space.

What Would It Look Like?

The new all-gender bathroom designs typically eliminate urinals entirely, replacing them with individual private stalls accessible to everyone. The CDE’s resources page recommends an academic article published in the Education Sciences Journal titled “Expanding the Scope of Universal Design: Implications for Gender Identity and Sexual Orientation,” by Ellyn Couillard and Jeanne L. Higbee (2018), as a guide for implementation. That an academic paper on gender identity ideology is among the state’s recommended planning resources tells you something about the ideological framework driving these design decisions.

But keep in mind, SB 760 doesn’t require a complete redesign of a single-sex bathroom for it to become all-gender. 

You Already Saw It at the State Capitol

If you want to get a glimpse of what legislators have in mind when they convert a single sex bathroom into an all gender bathroom, take a look at one of the converted male bathrooms at the state capitol, used by legislative staffers, adult visitors, and elementary school children visiting on field trips. California Family Council recently took a video of the empty bathroom located to one side of the Capitol Dome.

“I’m pretty sure most parents would object to their young children sharing a bathroom while men are using the urinals,” Burt said. “Even without the adult issue, I’ve witnessed the chaos that occurs when young boys are pouring into the same bathrooms as the girls while visiting the Capitol. The girls are not happy about it.” (Watch video tour of Capitol bathroom https://www.youtube.com/watch?v=okTcKcP3ACQ) 

So, what should parents expect when multi-stall bathrooms are converted to all gender at their child’s school?

What the Law Actually Requires — And What It Doesn’t

It is important to be clear about what SB 760 does and does not mandate. The law requires that every school campus have at least one all-gender restroom option available to students. It could be single-stall or multi-stall. It must be supplied with menstrual products starting in 3rd grade, and it must be unlocked and easily accessible. But there are no requirements that urinals be removed or that additional privacy measures be added to stalls.

Sex-separated restrooms are still permitted, and most schools will continue to have them.

Burt explained what this means in practice for families. “How each school fulfills this new requirement is entirely up to the local school board. A conservative district might simply relabel a single-occupancy nurse’s bathroom and call it done. A progressive district could use this law as a green light to convert entire multi-stall restroom facilities to mixed-sex use. Parents need to find out right now what their district is planning,” he said.

The CDE’s planning resources make clear that the broader vision goes well beyond a single-stall accommodation in the corner of the building. It points toward a wholesale redesign of school bathroom facilities, one that treats sex-separated restrooms as a problem to be solved rather than a common-sense protection for children.

The Question Nobody in Sacramento Answered

SB 760’s supporters argued the law was needed to protect transgender-identified students from harassment, but the legislature never seriously asked the parallel question: does giving boys access to girls’ bathrooms and locker rooms create new opportunities for harassment and assault of girls?

California has seen case after case in recent years where policies designed to accommodate gender identity have created unsafe situations for female students. The discomfort of girls sharing intimate spaces with biological males is not a lesser concern. Lawmakers who refused to weigh it have not protected children. They have simply chosen which children’s safety matters.

Parents: Now Is the Time to Speak Up

Because each school board will decide how to implement SB 760 on its own campuses, parents have a real opportunity to influence what happens at their child’s school, but that window will not stay open indefinitely. Decisions about restroom redesigns and facility changes get made early in the budget and planning process, often before most parents are even aware the conversation is happening.

If you want a say in how your district handles this new requirement, call your school board member and school administrators now. Ask them directly: how does our district plan to fulfill the SB 760 all-gender restroom requirement? Will existing sex-separated restrooms be preserved? Will multi-stall facilities be converted? Every parent deserves to know the answers. 

Here is one of the committee hearings from 2023, when SB 760 was discussed, and CFC provided opposition testimony. https://www.youtube.com/watch?v=Bwk7J82Prn8&t=1s

About California Family Council

California Family Council works to advance God’s design for life, family, and liberty through California’s Church, Capitol, and Culture. By advocating for policies that reinforce the sanctity of life, the strength of traditional marriages, and the essential freedoms of religion, CFC is dedicated to preserving California’s moral and social foundation.

Allen D. Payton contributed to this report.

CoCoTax welcomes apparent defeat of Measure B sales tax, Measure G bond issue

Monday, June 8th, 2026

By Contra Costa Taxpayers Association

The latest election results show Contra Costa Measure B trailing with less than 43% of the vote in favor. A relatively small number of late arriving votes are unlikely to change the outcome, given the 36,562-vote gap between the NO and YES totals.  Measure G is also likely to fail.

Measure B would have raised sales taxes by 0.625% around the county, would have cost consumers more than $750 million during its five-year life, and would have pushed total sales tax rates over 10% in most of the County.   Measure G was yet a fourth bond measure for the county colleges, adding to our indebtedness and long-term payment of interest.  The bond measures appear not to have ever been enough and with falling student numbers, huge investments make no sense.

As the official ballot opponent to Measure B, Contra Costa Taxpayers Association (CoCoTax) showed voters the deceptiveness of the proponents’ case, which included exaggerated claims about Medi-Cal funding losses, alarmism over emergency room overcrowding, and the false assertion that the tax did not apply to groceries (prepared foods, OTC medications, and non-food groceries would have been subject to the tax).  For Measure G, we showed the math behind it and how the only people looking to support it with money were unions whose contracts expire this month.  The unions also planned to take advantage of Measure B funds.

CoCoTax rallied volunteers to get the message out with signage, verbal appeals, videos, text messages and more. The organization made its first set of campaign finance expenditures, reporting approximately $20,000 of independent expenditures to the County’s campaign finance system. This spending paled in comparison to the $450,000 raised by the Yes on B campaign, mostly from unions seeking to maximize dues revenue.

Denise Kalm, a CoCoTax Executive Committee who agreed to serve as the group’s President Pro Tem this Spring led the successful effort against Measures B and G.

Reacting to the results, Kalm said, “Measure B would have given the Board of Supervisors another big infusion of cash; they already had burdened us in 2020 with Measure X and haven’t even found ways to spend/waste it all.  And yet, they came back with a 0.625% increase in sales tax demand, purportedly to fix the healthcare shortfall they claim President Trump caused.  None of it was true; none of their math added up.“

Though CoCoTax initially started only going after B, we made an effort to get G to fail, which worked.

CoCoTax welcomes more Contra Costa residents to join us and volunteer. We’re expecting many tax and bond measures in November and then again in 2028. While some may be reasonable, others, like the regional transit tax, require informed and active opposition. Neighbors who want to join us in “Fighting for Good Government at Affordable Cost in Contra Costa,” are encouraged to check out our website at https://www.cocotax.org.

Contra Costa voters asked to expand, contract, extend County’s Urban Limit Line for 25 more years with Measure A

Sunday, May 31st, 2026
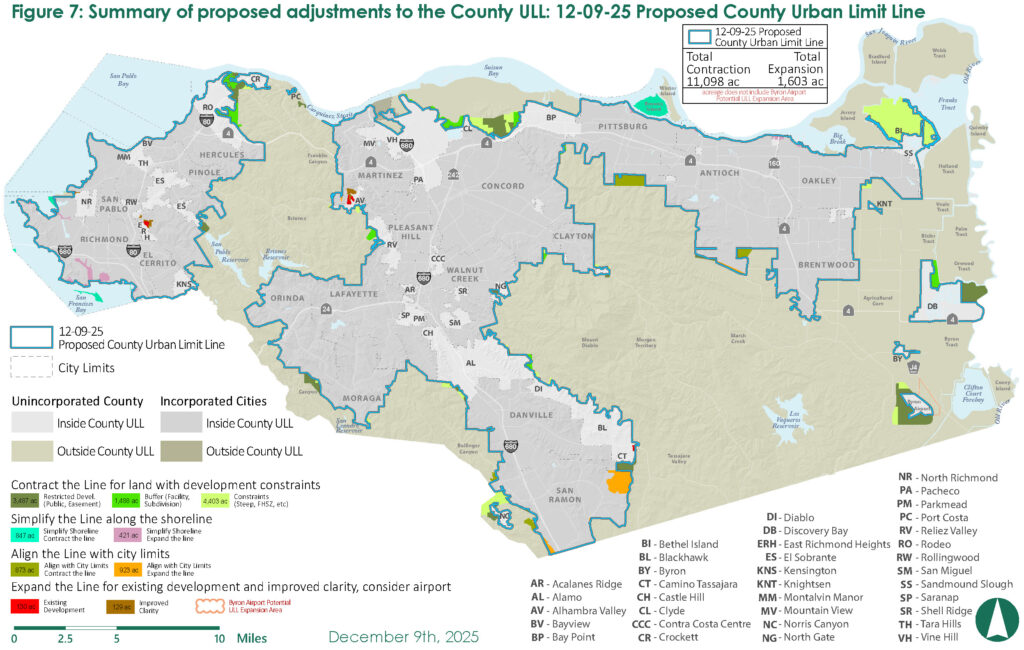
The Proposed 2026 County ULL renewal map shows areas of contractions and expansions. Source: Contra Costa County

Would allow for expansion near Byron Airport, contractions elsewhere including next to Antioch

Will not affect Antioch’s ULL

By Allen D. Payton

On Tuesday’s Primary Election ballot in Contra Costa County is Measure A, the 2026 Voter-Approved Contra Costa County Urban Limit Line also referred to as the Urban Limit Line and Land Preservation Plan Amendment Measure. Voters are asked whether or not to extend the County’s current Urban Limit Line (ULL) for 25 more years, as well as expand and contract it, placing a net of almost 9,500 more acres outside the line.

The ballot language reads, “Shall the measure amending the Contra Costa County General Plan and the County’s 65/35 Land Preservation Plan Ordinance to continue protections to the County’s non-urban, agricultural, and open space areas by extending the term of the County’s Urban Limit Line through December 31, 2051; adopting an updated Urban Limit Line map; requiring voter approval, except under limited circumstances, to expand the Urban Limit Line by more than 30 acres; and retaining the 65/35 Land Preservation Standard, be adopted?”

The county’s first ULL was voter-approved in 1990 and was renewed in 2006 which lasted 20 years.

Each of the 19 cities have their own voter-approved ULL, which supersede the County’s ULL, in order to receive local street maintenance funds from Measure J, the county’s half-cent sales tax for transportation. The City of Antioch did that when voters there established their own line and moved the County’s line back out in 2004, after the Board of Supervisors moved it in and cut off the land previously planned for the Roddy Ranch golf course and housing development. That land was later sold to the East Bay Regional Park District and is planned for a park.

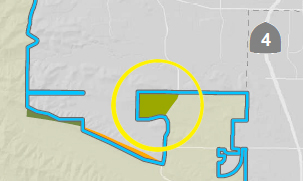
The Ginochio West property (inside yellow circle) adjacent to Antioch’s city limits (inside the blue line) would be moved outside the County’s ULL if Measure A passes. Graphic source: Contra Costa County

So, Measure A will not affect each city’s ULL, only land in the unincorporated portions of the county. But it will move outside the County’s ULL a section of land, currently outside the Antioch city limits bordered by Deer Valley and Empire Mine Roads, where long-time Antioch residents might remember the “party barn” was located, on property now known as Ginochio West in planning documents. It would be constrained to public or easement use.

Will Extend County ULL by 25 Years, Allow Expansion Near Byron Airport, Contractions Elsewhere

According to the County Counsel’s Impartial Analysis of the measure,“In 2004, voters approved Measure J-2004, which extended a local transportation sales tax (Measure C-1988) by 25 years and allowed the County to receive a share of those sale tax proceeds provided the County had a voter-approved ULL.

“In 2006, voters approved Measure L-2006, which extended the term of the ULL to December 31, 2026. In order (for the County) to continue to be eligible to receive transportation sales tax proceeds after 2026, the ULL must be extended beyond 2026. This measure would extend the County’s ULL for 25 years, through December 31, 2051.

In addition, “the measure would amend the County’s 2045 General Plan and the 65/35 Ordinance to accomplish the following: (1) extend the term of the 65/35 Ordinance from December 31, 2026, through December 31, 2051; (2) require four-fifths vote of the County Board of Supervisors and voter approval to expand the ULL by more than 30 acres (except under limited circumstances); (3) provide for periodic reviews of the ULL by the Board of Supervisors and a required review involving an evaluation of housing and job needs; (4) update and expand the criteria for moving land outside the ULL; (5) incorporate a revised ULL map that among other things delineates an area of future potential expansion near the Byron Airport; and (6) retain the 65/35 land preservation standard and protections for the County’s prime agricultural land. This measure will become effective immediately if approved by a majority of the voters voting on the measure.”

The proposed County ULL would include contractions totaling 11,098 acres and expansion of 1,603 acres for net 9,495 more acres placed outside the Urban Limit Line. (See map). However, the acreage does not include the Byron Airport Potential ULL Expansion Area.

Yes on A Campaign’s Main Argument

The main argument of the Yes on Measure A campaign, paid for by Save Mount Diablo and supported by nine other organizations, is “The Urban Limit Line helps prevent traffic from getting worse. The more people have to drive, and the more cars on the road, the worse traffic gets. This election, say YES to protecting our open space and agriculture, safety from wildfire, limiting traffic, and encouraging housing where it makes sense.”

No on A Campaign’s Main Argument

The main argument of the No on Measure A campaign, paid for by the Contra Costa Taxpayers Association is that “Measure A removes an additional 9,460 acres — equivalent to 14.78 square miles — from any possible urban housing use through 2051. That is larger than 10 of the 19 cities in Contra Costa County. Calling this a routine renewal misleads voters about what is actually on the ballot.”

The campaign also claims, “When Contra Costa restricts its land supply, families don’t disappear. They move — and commute back.”

Analysis: Growth is inevitable and acts much like a balloon, when it is restricted in one area, growth expands elsewhere. Such as in the Central Valley which feeds not only our state, but nation and world, and where land is cheaper and unfortunately, farmers can make more money selling to developers than farming. The result is commuters driving further to work and blowing more polluting smoke out of their tailpipes, defeating the goals of the environmentalists.

At the same time, there’s plenty of room inside the current ULL’s of the cities for more housing growth to occur, especially in East County. Plus, the measure includes a potential expansion near the Byron Airport where commercial and/or mixed-used development could occur, as the long-planned, four-lane Route 239 between Brentwood and Tracy are built, the runway is potentially extended, a fixed base operation and fuel farm are built there, and a possible transit stop located there, as well.

Read more information on the websites for both the Yes on Measure A and No on Measure A campaigns.

See the Full Text of the Measure.

Opinion: CoCoTax says vote no on Measure G – a $1.88 billion burden Contra Costa can’t afford

Wednesday, May 27th, 2026
All graphics & charts source: CoCoTax

By Mike Arata

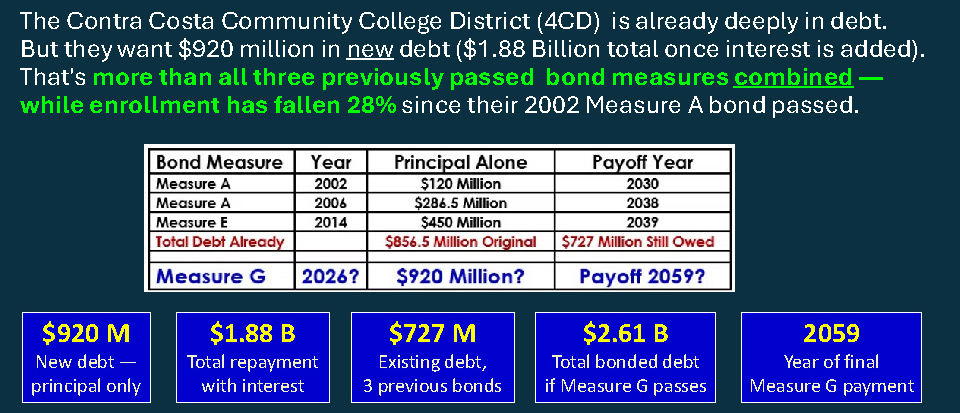
On June 2, Contra Costa County voters will decide whether to saddle themselves — and their children — with the largest bond debt in the history of the Contra Costa Community College District (4CD). Measure G asks for $920 million in new borrowing. With interest, the true cost climbs to $1.88 billion, with final payoff projected in 2059. CoCoTax has opposed this measure in official ballot arguments, in public presentations, and in a detailed response to a recent article in the Contra Costa College Advocate.

The case against Measure G is straightforward: it is far too much money, sought too soon given outstanding bond debt, by a district that hasn’t demonstrated the fiscal discipline to deserve it.

Already Drowning in Debt

4CD still owes on three bond measures as is:   2002’s Measure A ($120 million), 2006’s second Measure A, ($286.5 million), and 2014’s  Measure E ($450 million) —  totaling $856.5 million in principal alone. County taxpayers still owe nearly $727 million on those existing obligations, with the final payment on Measure E not expected until 2039. Measure G would pile $1.88 billion more on top of all that. If it passes, total bonded indebtedness reaches $2.61 billion, secured by Contra Costa County property values — with no senior exemption.

Enrollment Is Down 28% — Yet They Want to Build More

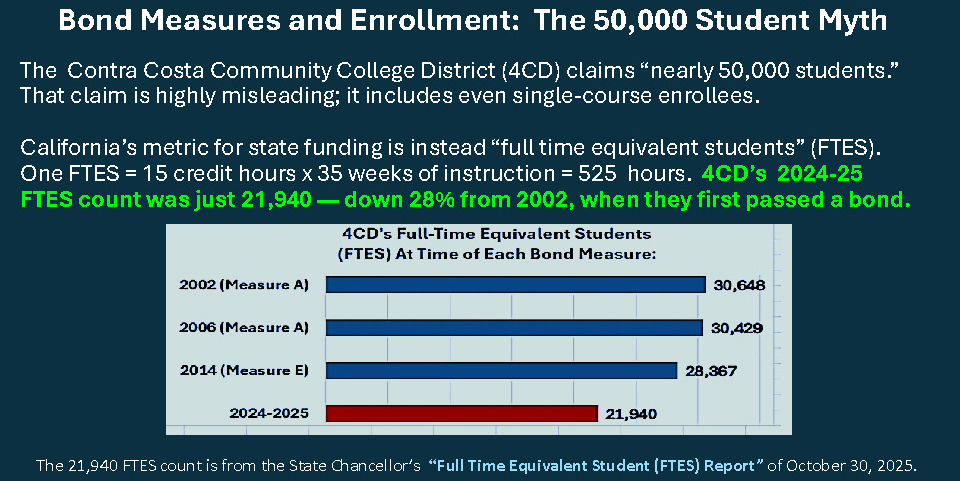
4CD advertises “nearly 50,000 students,” but that figure is misleading. California’s actual funding metric is Full-Time Equivalent Students (FTES). According to the State Chancellor’s October 2025 FTES Report, 4CD’s count was just 21,940 — down 28% from 30,648 when Measure A passed in 2002. Expanding costly new facilities while enrollment trends sharply downward is the opposite of responsible stewardship.

“Deferred Maintenance” — Deferred Forever?

Roofing repairs, seismic retrofits, HVAC upgrades, and electrical work appear repeatedly in 4CD bond project lists going back to 2002. How many bond measures must pass before these basics get done? There’s a core problem: 4CD’s maintenance budget has crept from just 0.10% to 0.20% of Plant Replacement Value over the past decade, when the commercial building standard is 2–5%. Routine maintenance gets deferred so the general fund can support other priorities — including lavish administrative compensation — and then bond money pays for the fixes, with interest on top.

Executive Pay That Outstrips the Governor’s

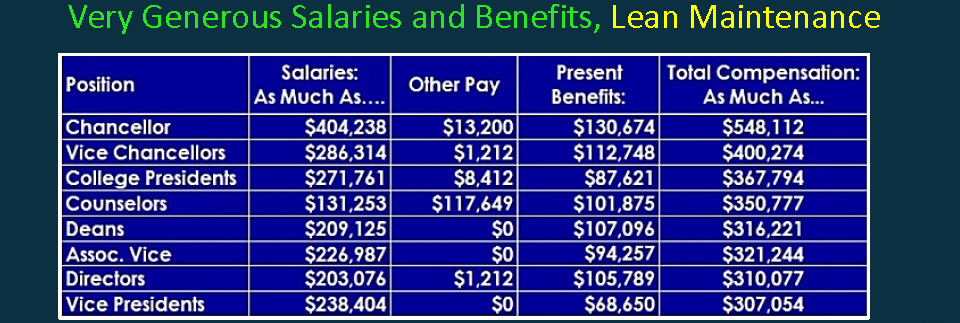
While seeking $920 million in new principal from taxpayers, 4CD’s Chancellor drew a $404,238 salary (as of 2024) — plus $130,674 in benefits, for total compensation reaching $548,112. That salary alone exceeds the official pay of the President of the United States and far surpasses Governor Newsom’s $245,929.  Vice Chancellors, College Presidents, and Directors also earn hundreds of thousands in total compensation. Lavish pay and lean maintenance are two sides of the same General Fund coin.

Who’s Funding “Yes on G”?

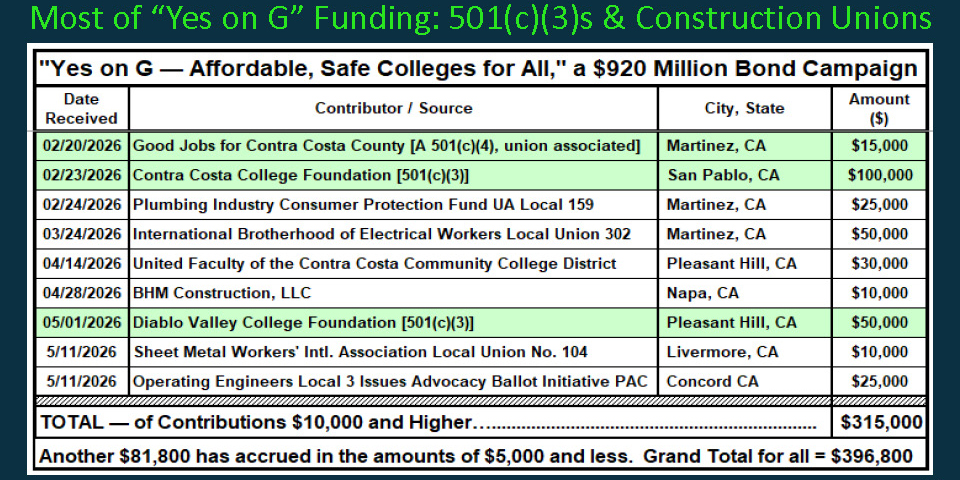
The pro-Measure G campaign has raised nearly $400,000 so far — with the bulk coming from the tax-exempt Contra Costa College Foundation ($100,000), the DVC Foundation ($50,000), and multiple construction unions (IBEW Local 302, Plumbers Local 159, Sheet Metal Workers Local 104, and others). Contractor unions have a direct financial interest in a $920 million construction program. Ordinary property-tax-paying residents have no equivalent organized voice — a textbook example of what economists call “Public Choice Theory.”

The Bottom Line

Property owners already pay an average of $13.97 per $100,000 of assessed value toward 4CD’s existing bonds. Measure G adds another $10 — and that rate could rise if the county’s assessed values don’t grow at the 4% annual pace 4CD projects, projections that, by 4CD’s own admission, “are not binding upon 4CD.”

4CD should maintain its existing buildings with its existing budget rather than repeatedly turning to taxpayers for borrowed billions. Vote NO on Measure G.

More information: NOonMeasureG.info

Arata is an Executive Committee member of the Contra Costa Taxpayers Association

Upcoming Events

CoCoTax Lunch, June 26: Former State Senator Steve Glazer Discusses BART Accountability
Friday, June 26, 2026 | 11:45am – 1:15pm PDT

CoCoTax Lunch, July 24: County Budget Overview with County Administrator Monica Nino
Friday, July 24, 2026 | 11:45am – 1:15pm PDT

For more information about the Contra Costa Taxpayers Association visit cocotax.org.

Opinion: Former and current AUSD staff, parents share concerns about Antioch school district

Tuesday, May 26th, 2026

Provide salary information for senior management

Dear Antioch Unified School District Board Members,

Given the severity of the district’s deficit, the community deserves to understand why the Board continues to authorize expensive contractors to perform work that qualified district staff are fully capable of handling. In education, sustainable improvement comes from setting clear expectations, providing support, and building internal capacity. Antioch is a resilient community filled with talented professionals. Our people deserve the opportunity and the trust to meet the standard.

It is also important to acknowledge that many of these same consultants were used in Pacifica and Sequoia, districts where the Superintendent departed in under two years amid controversy. Why would the Board select a leader without a demonstrated record of long-term, successful superintendent leadership.

Board President Dr. Jag Lathan, you are currently running for County Superintendent. If effective oversight and leadership cannot be demonstrated in a mid‑sized district like Antioch, how will you lead an entire county. Voters are watching and waiting for you to do what is right.

The district’s increasing reliance on high‑cost consultants is fiscally irresponsible and deeply concerning especially during a financial crisis. This year alone, consultant contracts are projected to exceed half a million dollars, including external providers for executive coaching, financial consulting, data analysis, and organizational climate assessments. Only a small portion of these contracts appear justified given staffing shortages. The rest raise serious questions about duplication of services, transparency, and fiscal priorities. The district already employs dedicated, effective leaders who have invested their careers and their hearts into serving Antioch’s students. Overlooking this internal capacity wastes resources and damages morale. Replacing qualified internal leaders with consultants occupying long‑term roles is unjust, irresponsible, and demoralizing. At what point will the Board accept accountability for these decisions?

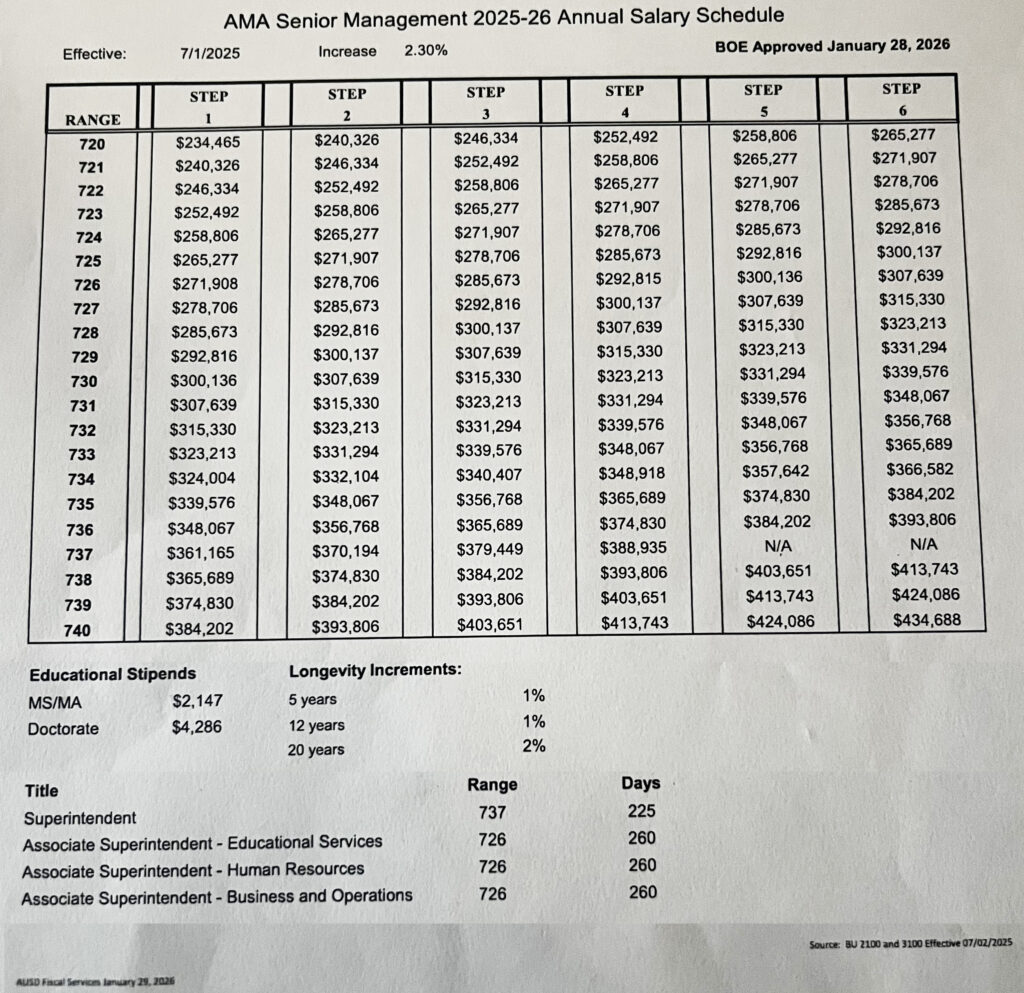
AUSD Senior Management Salary Chart 2025-26. Source: Amy Bettencourt

There has also been a mass exodus of leadership and long‑term teachers. This exodus is directly tied to the current district leadership. Why is the Board not interviewing these long-standing, highly respected employees to understand why they are leaving AUSD?

Attorney fees have been repeatedly discussed at board meetings and often dismissed by comparing them to previous years. But this year, the number of law firms brought in under Dr. Williams has significantly increased legal costs. If the highly publicized employee bullying lawsuit from last year were removed from the comparison, would last year’s attorney fees still exceed the current year’s. That is a question the community deserves answered.

According to individuals familiar with the superintendent hiring process, community panelists were puzzled by the Board’s decision. Several candidates reportedly ranked higher among parents, staff, and students including two Latino leaders who panelists felt could more closely relate to and serve the district’s student population. Insiders state that Dr. Williams ranked last among five finalists in some community feedback summaries. Despite these concerns, Dr. Williams assumed leadership of AUSD in July 2025.

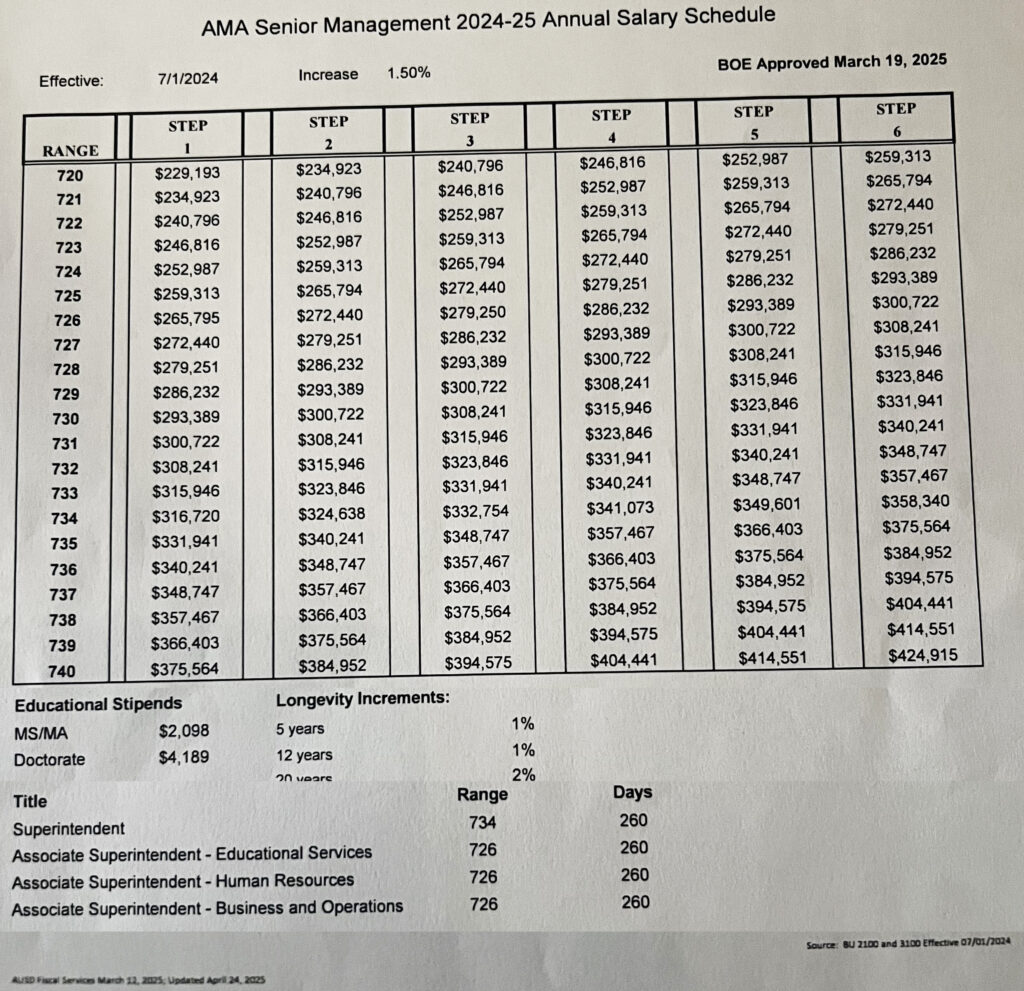
AUSD Senior Management Salary Chart 2024-25. Source: Amy Bettencourt

It is public knowledge that entering the 2025–26 school year, AUSD faced an approximate $12 million deficit. The CBO in place at the time who had full knowledge of the deficit and a fiscally sound plan to address it without harming student services or requiring staff layoffs was placed on leave almost immediately by Dr. Williams. It has been stated repeatedly at board meetings that the approved raises and continued 100% district‑paid health benefits did not contribute to the now $31 million deficit. That is not accurate. The increased deficit is directly tied to the raises and benefits negotiated by Dr. Williams and her attorney.

Another contributing factor is the Superintendent’s newly created salary schedule. Historically, AUSD superintendents were placed on salary schedule 734 with a 260-day work year. Dr. Williams negotiated a new 737 range with a 225-day work year 35 fewer days than her senior management team. The previous superintendent, at year six, earned $358,340 annually ($1,378 per day). Dr. Williams began at $361,165 annually ($1,605 per day) and will top out at $1,728 per day.

Despite this significantly higher, per‑day rate, district staff report that Dr. Williams is rarely present in the district office, and when she does arrive, it is often afternoon. She is not beginning her day at school sites, and her whereabouts during the workday are frequently unaccounted for. Given these concerns, why was an entirely new salary schedule created without any data demonstrating long‑term success, improved student outcomes, or consistent leadership presence. Her history shows the opposite, with districts left in turmoil.

At what point will the Board seek honest insight from current and former employees rather than relying on soundbites and publicity efforts. The community is asking for transparency, accountability, and the responsible use of AUSD funds. Every dollar spent should reflect a commitment to students, staff, and the long‑term stability of this district—not to unnecessary contracts, unchecked legal fees, or inflated administrative compensation.

Respectfully,

Amy Bettencourt, former Director of Educational Services, Antioch Unified School District and Concerned Staff, Parents and Citizens

In a note included with the emailed letter to the editor Bettencourt wrote, “I know I left Antioch USD at the end of February due to the toxicity and storm the new superintendent brought to the district, but I continue to hear from a large group of employees who are desperately trying to elevate their concerns publicly.”

Opinion: Falsely framed CC County budget story promotes Measure B tax increase

Saturday, May 23rd, 2026

By Mike Arata

A report on the 2026-27 budget, by a Contra Costa County public information officer, is essentially a tax-promotion advertisement for Measure B’s intended 0.625% sales-tax increase.  It omits essential facts, to the potential benefit of the County’s already overpaid administrative staff and its 15 highly compensated employee unions. Consider the following: 

1.  The County’s tentative $7.248 Billion budget for 2026-2027, were it to remain unchanged at the July 1 start of new Fiscal Year 26-27, would still be a massive 60.7% higher than FY20-21’s $4.51 Billion. (See p. 8 at link.)  November 2020 was when the County passed Measure X, itself a 0.500% sales tax increase. The Bay Area’s CPI inflation rate, meanwhile, has totaled 18.4% since Measure X’s passage (358.6 /302.9 = 1.184). The County’s spending increase since the end of 2020 is 3.3 x the inflation rate.

2.  Measure B, on the June 2nd ballot, would add another 0.625% in new sales taxes, raising every part of the County above the statutory 2% limit on LOCAL sales-tax rates, over and above the existing statewide 7.250% rate.  7.250% + 2.000% = an effective statutory-limit total of 9.250%.  If Measure B passes, sales-tax rates in the County will instead range from 9.375% to 10.875%.   An additional 0.500% transit sales-tax measure is upcoming on the November ballot.

3.  In bypassing the relevant statute, all the County’s tax promoters had to do was to get an on-call legislator to include Contra Costa County in an existing, illegitimate Los Angeles bypass bill (AB1768), say shazam(!) — and poof!  No more 2% limit on any local sales-tax rates here.  (Actually, Measure X itself took local rates in six Contra Costa municipal jurisdictions above 2%.)

4.  As is, the County’s 2026 own union-member employment head count is up 4% over 2025 (slide 10) — 10,308 vs. 9,913.  And 9 of the County’s 15 union contracts expire 4 weeks after Election Day.  That’s a clue for the likely real purpose of Measure B.

5.  As of 2024 (last year available), 4,781 County employees were already above $150,000 in salary plus benefit compensation.  3,056 of those exceeded $200,000.  1,045 of those exceeded $300,000.  278 of those exceeded $400,000, with 78 above $500,000.  How many executive-level employees does the County need?  How many should we pay for?

6.  Measure X presented an urgent, COVID-time focus on healthcare and “life-saving services.”  Now, allegedly, “lives will be lost” without Measure B (pages 33-34 of 86 in Voter Guide).  In fact, Measure X’s millions have been used for multiple other purposes.  And Measure B’s authorizing ordinance, like Measure X’s, again exposes this new tax as “solely for general governmental purposes and not for specific purposes.” County politicians and administrators could spend Measure B’s millions on whatever they consider “governmental” — as they’ve already been doing in Measure X’s first 5 of 20 years.  Measure B could facilitate or directly bankroll the next round of employee enrichments.

7.  Measure X, the template for Measure B, was supposed to collect $81 Million annually in additional new sales-tax revenues.  Instead, it’s taken in over $120 Million annually (page 11 of 16), and Measure X has another 15 years to run.  Meanwhile, Measure X has accumulated $263 Million in unspent funds (same page).  Those dollars, rather than more new sales-tax revenue, could and should be dedicated to any healthcare deficiency that actually develops. 

8.  And speaking of excess funds, the County has a General Fund balance of $1.21 Billion, of which the unassigned portion is $585 Million. Both figures are more that 4 times the County’s own announced standard for reserves on hand (pages 18 and 56 of 269). 

9.  County supervisors tried to get away with an alleged $307 million ANNUAL healthcare budget deficiency, (e.g. here and here) until I and others pointed to figures stated by their own financial advisory firm (itself holding an $8 Million contract).  That reality was a potentially CUMULATIVE $307 Million by FY28-29, not an annual one.  Their chief financial advisor then returned with a new slide showing larger potential amounts in FY29-30 and FY30-31 — in a new presidential administration and 2 new Congresses from now.  As stated in ballot arguments, Measure B is at best premature. 

10.  Due to some funding restoration already announced, the new budget deficiency projected in an updated County slide was a cumulative $219 Million by FY28-29 (though minutes of the Board of Supervisors’ meeting presented the amount as $239 Million).  Even that is speculative; and again, Measure X could cover that amount if needed, under its originally announced purposes.  And to begin with, much of the funding problem derives from withdrawal by the Center for Medicare and Medicaid Services of “federal Medicaid dollars to cover health care for individuals who are in the country illegally” (as “a backdoor pathway to subsidize open borders”).

11.  The County’s Measure B propagandists claim elsewhere that “It exempts food, housing, and medical care, so most of the money from this tax will come from corporate or large luxury purchases.”   But as the East Bay Times said (among many other factors in opposing Measure B itself), “State data indicates that the average person in the county currently pays at least $1,050 a year in sales tax.”  Food/grocery exemptions?  Not for prepared foods, soft drinks, beer and wine, ice, many convenience grocery store items, etc. — and not for restaurant bills.  Housing exemptions?  Not for materials used to build and maintain houses.  Exemptions for medical care?  Not for over-the-counter medicines. 

12.  Rather than voting to continue engorging the already vastly over-funded and overcompensated County spending apparatus and apparatchiks:  attentive and fair-minded voters will vote NO on Measure B — thereby to leave taxpayers, especially those already struggling with affordability problems, with more of their own money to spend for items THEY see as needs.

Regarding the County’s self-serving Measure B scheme — and its dishonest 2020 predecessor, Measure X:  the response now should be “Fool us once, shame on them. Fool us twice, shame on us!”

More information:  StopMeasureB.com

Arata is an Executive Board member of the Contra Costa Taxpayers Association.

Analysis: City of Antioch out of compliance with intent of Measure W sales tax funds allocation

Monday, May 4th, 2026
Yes on W 2018 campaign ad. Source: Antioch Herald

Oversight Committee not holding Council accountable to 80-10-10 split

By Allen D. Payton

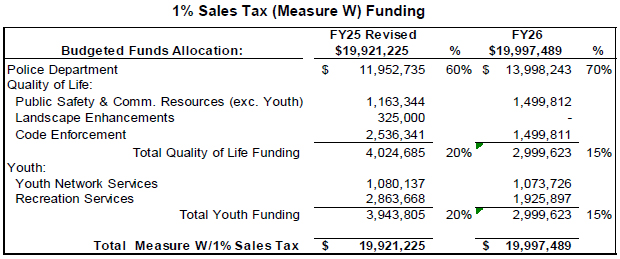
The City of Antioch is supposed to be spending the funds from Measure W’s one-cent sales tax measure, passed by the voters in November 2018, on an 80-10-10 split, with 80% for maintaining public safety, 10% for youth services and the remaining 10% to support quality of life, and fiscal stability and accountability. However, the 2023-24 budget spent only 60% of Measure W funds on police, last year’s budget increased the amount to 65.4% and the current fiscal year’s City budget allocated 70%. Plus, last year’s budget only allocated 4.6% to Youth Network Services.

Funds in Fiscal Year 2024-25 instead were spent on Code Enforcement and homeless services, as well as street lighting and landscaping.

According to the adopted 2025-26 City Budget, “The adopted fiscal year 2023-25 budget allocated 60% of funds to the Police Department, 20% to Quality of Life and 20% to Youth. For fiscal year 2025-26, City Council is allocating 70% to the Police Department, 15% to Quality of Life and 15% to Youth” ignoring the original intent of the council that voted to place the measure on the ballot.

City of Antioch Measure W Funding allocations FY25 versus FY26 Budgets. Source: City of Antioch

Sales Tax Citizens’ Oversight Committee Report

According to the Sales Tax Citizens’ Oversight Committee Fiscal Year 2024-25 Annual Report on Measure W  provided to the City Council on March 24, 2026 (relegated to the Consent  Calendar under agenda item 5.N.), “In FY24, the City received $20,160,685 in Measure W revenue and allocated funds at 60% Police, 20% Quality of Life, and 20% Youth.”

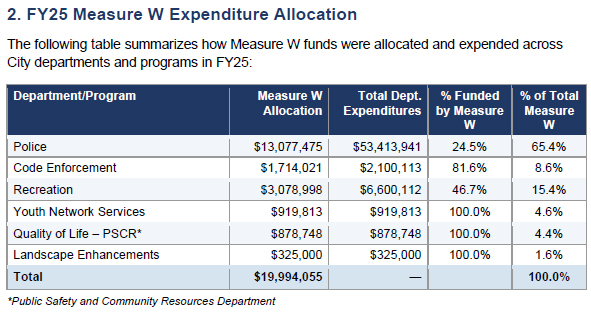
For the fiscal year that ended June 30, 2025, “The largest share of Measure W funds—65.4%, or $13,077,475—was directed to the Antioch Police Department. These funds supported a portion of police personnel costs ($40,376,709 in total department personnel expenditures) and services and supplies ($11,436,353). Measure W revenue represents approximately 24.5% of the Police Department’s total FY25 expenditures of $53,413,941, sustaining patrol operations, 911 response capacity, and related public safety services.”

Also, according to the report, the other Measure W revenues were spent in FY 2024-25 in order of greatest amount to least, as follows:

  • Recreation 15.4%;
  • Code Enforcement 8.6%;
  • Youth Network Services 4.6%;
  • Quality of Life 4.4%; and
  • Landscape Enhancements 1.6%
Source: City of Antioch Sales Tax Citizens’ Oversight Committee FY2024-25 Report.

2024-25 Measure W Expenditure Report Details

Under section 3 entitled, “Alignment with City Council Stated Priorities” the report offers details for each of those expenditure categories, but does not identify which council stated the priorities nor cite when that occurred. The report reads as follows:

  • Youth Violence Prevention and Community Safety

The Public Safety and Community Resources (PSCR) Department received $878,748 (100% Measure W funded) for Quality of Life programs. Within the department’s broader operation, the Violence Intervention and Prevention unit had a budget of $281,094 with $137,814 expended, during the fiscal year while the Housing and Homelessness unit budgeted $351,575 and expended $207,645. Community Engagement budgeted $27,697 with $27,629 expended. These programs directly address community safety, violence intervention, and quality of life for Antioch residents.

  • Youth Afterschool and Summer Programs

A combined total of $3,998,811 in Measure W funds supported youth-focused programs. Youth Network Services received $919,813 (100% Measure W funded) for personnel ($477,538) and services and supplies ($442,275). Recreation received $3,078,998, representing 46.7% of the department’s total expenditures. Recreation’s programs include youth afterschool activities, summer programming, and community recreation services.

  • Code Enforcement and Community Cleanup

Code Enforcement received $1,714,021 in Measure W funds, constituting 81.6% of the division’s total expenditures. The division’s work addresses illegal dumping, nuisance abatement, and property maintenance standards—directly supporting the Council’s priorities of cleaning up parks and combating blight. Personnel costs totaled $1,785,197, with services and supplies at $314,916.

  • Landscape Enhancements

A total of $325,000 (100% Measure W funded) was transferred to the Lighting and Landscape Districts for maintenance and enhancements across the city’s public landscaped areas, contributing to park and neighborhood beautification.

History of Measure W

As previously reported, during their meeting on Tuesday, July 24, 2018, the Antioch City Council voted 5-0 to place a ballot measure that would extend and double the transaction and use tax, or sales tax, permanently from the half-cent sales tax of Measure C, passed in 2013, to one cent. (See related article)

The council members discussed the draft version of the proposed one-cent sales tax measure. It allocated 60% of revenue for the maintenance of public safety, 20% for youth services, and the remaining 20% for supporting quality of life and fiscal stability and accountability.

But during the meeting the council discussed changing these amounts from percentages of 60-20-20 to an 80-10-10 allocation had the support of three council members. That split was advocated for by both Councilwoman Lori Ogorchock, who included it in her motion which was seconded by Councilman Tony Tiscareno, and Mayor Sean Wright during his comments.  

20-Year Sunset Clause, Public Oversight Added

Then during a special meeting on August 7, 20218, the Council on a 3-2 split vote, approved adding a 20-year sunset clause and including language to continue the Citizens Sales Tax Oversight Committee to the measure with then-Mayor Pro Tem Lamar Thorpe and Councilwoman Monica Wilson voting against. Placing the measure on the ballot required a two-thirds vote of the council, or favorable votes by four of the five councilmembers.

The council held another meeting two days later on August 9th at which the two who opposed it switched course. They joined the other three councilmembers for a unanimous, 5-0 vote to included both the 20-year sunset clause and citizens oversight language in the ballot measure.

Council Meeting Minutes on Measure W Votes

According to the minutes of the council meeting on July 24, 2018, the original motion is reported as follows:

“Councilmember Ogorchock moved to 1) Adopt the resolution of the City Council of the City of Antioch Calling for a Municipal Election on November 6, 2018 to Request City Voters Extend and increase the City’s Transaction and Use Tax from One-Half Cent to One Cent to Provide for Public Safety and 911 Service, Support Youth, and Maintain Other Quality of Life Services; and, 2) Enact an Ordinance of the City Council of the City of Antioch Submitting a Proposition to The Voters of the City of Antioch to Amend Article 4 of Chapter 5 of Title 3 of the Antioch Municipal Code to Increase the City’s Transactions and Use Tax from a Half Cent to One Cent and to Impose This Tax Until Repealed by the Voters. 3) Maintain Public Safety target for Antioch Police Department at 80 percent, support youth services 10 percent, support quality of life/fiscal stability and accountability at 10 percent.

Councilmember Tiscareno seconded the motion”

In addition, the minutes read, “Mayor Wright…noted that he would support 80 percent of the tax being allocated to public safety.”

However, following input from the city attorney and city clerk, the motion adopted by the council did not include specific allocation figures. According to the meeting’s minutes for the item: “Following discussion, Councilmember Ogorchock amended her motion. Councilmember Tiscareno agreed to second the amended motion, which was approved as follows:

“On motion by Councilmember Ogorchock, seconded by Councilmember Tiscareno, the City Council unanimously 1) Adopted a Resolution of the City Council of the City of Antioch Calling for a Municipal Election on November 6, 2018 to Request City Voters Extend and Increase the City’s Transaction and Use Tax from One-Half Cent to One Cent to Provide for Public Safety and 911 Service, Support Youth, and Maintain “Other Quality of Life Services; and 2) Enacted an Ordinance of the City Council of the City of Antioch Submitting a Measure to The Voters of the City of Antioch to Amend Article 4 of Chapter 5 of Title 3 of the Antioch Municipal Code to Increase the City’s Transactions and Use Tax from a Half Cent to One Cent and to Impose This Tax Until Repealed by the Voters. With the following changes:

  • Amending the Ordinance under the ‘Now, Therefore, Be It Resolved’ to read: ‘that the People of Antioch do ordain as follows:’
  • Striking the word ‘Proposition’ from the Ordinance and replacing it with ‘Measure’.”

Again, the additional clauses adding a 20-year sunset and citizen oversight to the measure were adopted at later meetings in 2018 before the measure’s final language was placed on the ballot.

Measure W Ballot Language

The final ballot language included in the measure which passed with 66.11% of the vote but only needed a simple, 50% plus, one vote was as follows: Antioch’s Quality of Life Measure. To maintain Antioch’s fiscal stability, police patrols, 911 emergency response, youth violence prevention programs; ensuring water quality/safety; repairing streets; cleaning up parks/illegal dumping; restoring youth afterschool/summer programs; other essential services; shall the measure be adopted approving an ordinance to renew the sales tax at the one-cent rate, raising approximately $14,000,000 annually,  expiring in twenty years, with mandatory annual independent financial audits, and independent citizens oversight?

Although the first motion to place Measure W on the ballot, which had majority council support, included the 80-10-10 split, it is not part of the actual ballot language, meaning the city council is not bound by those amounts and can spend the funds in any way they deem necessary.

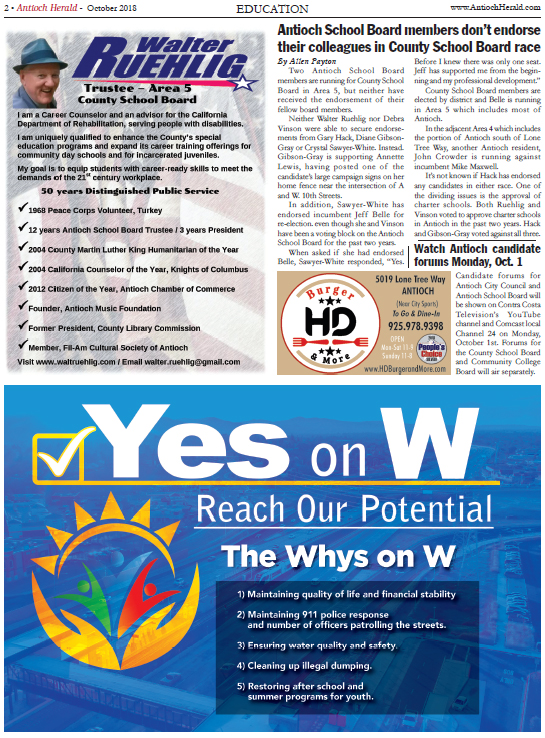
Page 2 of the Antioch Herald October 2018 edition.

Yes on W Campaign Message

Yet, that’s how the measure was sold to the voters and how Antioch residents expect the funds to be spent.

Since the measure passed, the new Department of Public Safety and Community Resources was formed, with attempts by some council members to redefine and expand the meaning of “public safety” in Antioch to include more than just police services. Yet, the campaign in support of Measure W was very specific.
In a letter to the editor on Oct. 30, 2018, then-Mayor Wright wrote, “Measure W gives us a choice to increase our financial ability to make our community safer, create more activities for our youth after school and to improve our quality of life.”
Plus, in a Yes on W campaign ad run on page two of the Antioch Herald October 2018 edition, under “The Whys on W” headline it read, “Maintaining 911 police response and number of officers patrolling the streets.” At the time, there were 97 sworn officers on the Antioch Police force.

That was in spite of the commitment by the city council of hiring 22 more police “immediately” from the funds generated by Measure C, the half-cent sales tax precursor to Measure W, which passed in 2013 when there were 90 sworn officers on the force.

The ad also offered the other Whys, including, “Maintaining quality of life and financial stability; Ensuring water quality and safety; Cleaning up illegal dumping; and Restoring after school and summer programs for youth.”

Committee’s Incorrect Claims

While the Oversight Committee’s report claims, “Expenditures across all funded departments were within budgeted amounts for FY25, demonstrating sound fiscal management of Measure W resources,” it’s clear the revenues have been not been appropriately allocated. In fact, past and current councils have been robbing Peter to pay Paul, as the old saying goes, which is what those who opposed the measure were afraid of.

Furthermore, the committee concluded its report claiming, “Measure W revenues for FY25 were expended in a manner consistent with the City Council’s stated priorities,” they’re ignoring the fact the council majority at the time they voted to place the measure on the ballot supported the 80-10-10 allocation split. So, even if the city council has since then, or in 2024 before adopting the FY 2024-25 budget, voted to change the allocation split of Measure W revenues, the funds were not “expended in a manner consistent with the City Council’s stated priorities” and are definitely out of alignment with the original intent.

Committee Needs to Represent and Advocate for Original Intent of the Council, Will of the Voters

Every year, the Oversight Committee’s report should include the city council’s original intent of allocating the revenue from Measure W on an 80-10-10 split and remind the current council members and public of that fact. Simply reporting how the council and City spent the funds based on information provided by City staff isn’t good enough. They need to hold the current council members accountable and advocate on behalf of the voters and residents of Antioch that they fulfill that intent. Otherwise, what’s the point of having an oversight committee? The members need to remember that although they were appointed to the committee by the city council, they’re not there to please the council but to represent the will of the people. Hopefully, the five new members who are expected to soon be appointed will.

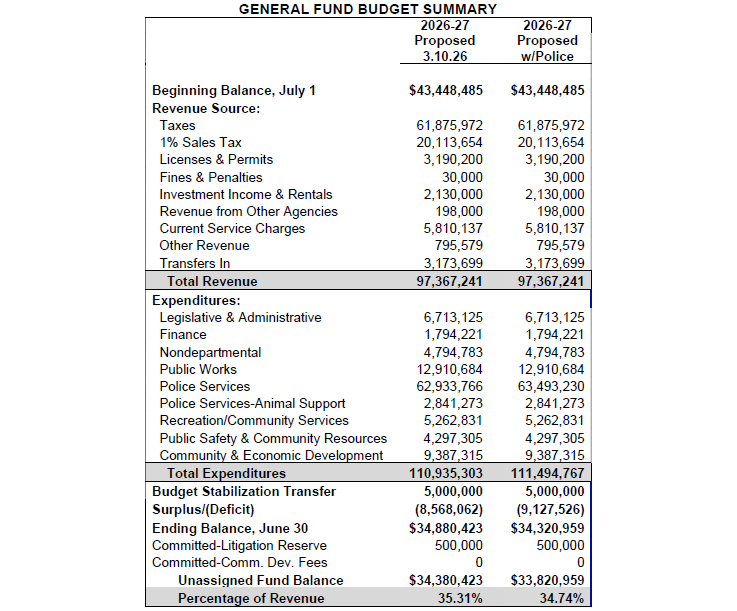
Measure W funds listed as “1% Sales Tax” under Revenue Source. Source: City of Antioch

Council Needs to Return to Original Intent of Measure W Revenue Allocation

As the city council works to finalize the Fiscal Year 2026-27 budget they need to be reminded of the original intent of the allocation of Measure W revenues and increase the amount being spent on police to 80%. While it’s good the council has expressed support for increasing the total number of sworn officers on the Antioch Police force, the allocation of the correct percentage of Measure W funds should be a key part of that. The good news is the projected revenue from Measure W for the next fiscal year is expected to increase by almost $120,000 to a little over $20.1 million. So, that will help some and it makes the math simple: $16.08 million to police, $2.01 million to youth services and $2.01 million to quality of life budget items. It all comes down to priorities.